Understanding Term Life and Whole Life Insurance: Which Policy Protects Your Family Better?
Life insurance is designed to provide a financial benefit to named beneficiaries after the death of the insured person. It exists because the loss of a person's income can create financial pressure for family members who depend on that income for everyday expenses, housing, education, debt payments, or other long-term obligations.
Context
Two widely recognized forms are term life insurance and whole life insurance. Term life insurance provides protection for a specified period, while whole life insurance is a form of permanent life insurance intended to remain in force throughout the insured person's lifetime, subject to the policy's conditions and premium requirements.
The question of which policy protects a family better cannot be answered by looking only at the policy type. The relevant factors include how long financial protection is needed, the amount of coverage required, the household's financial responsibilities, premium affordability, and whether cash value features are relevant to the policyholder's objectives.
How term life insurance works
Term life insurance provides a death benefit if the insured person dies during the specified policy period. Common term periods include 10, 20, or 30 years, although available periods differ between insurers and jurisdictions.
Some term policies can be renewed after the initial period, while others may include a conversion provision that permits a change to certain permanent coverage under specified conditions. Renewal premiums can be higher than the original premium, particularly as the insured person becomes older.
How whole life insurance works
Whole life insurance is a type of permanent life insurance. It generally provides a death benefit for the insured's lifetime and also has a cash value component that can accumulate according to the policy terms.
Cash value can provide another financial feature during the policyholder's lifetime, but it should not be treated as identical to ordinary savings. Policy charges, premiums, withdrawals, loans, dividends where applicable, and other contractual provisions can affect policy values and the amount ultimately available.
Term life vs whole life at a glance
| Feature | Term Life Insurance | Whole Life Insurance |
|---|---|---|
| Coverage period | Specified term | Lifetime, subject to policy conditions |
| Cash value | Generally none | Generally included |
| Premium structure | Usually lower initially | Usually higher |
| Main purpose | Temporary financial protection | Long-term protection with cash value |
| Renewal | May be available | Normally not required in the same way |
| Conversion | May be available | Already permanent |
| Policy complexity | Generally simpler | Generally more complex |
Importance
Choosing between term life and whole life insurance matters because families can have financial obligations that continue for many years. A policy may be intended to replace income, support dependent children, address outstanding liabilities, or provide funds for other long-term household needs.
The appropriate structure can also change as circumstances change. A household with young children and substantial income dependence may have different protection needs from a household with financially independent children and fewer outstanding obligations.
What family protection actually means
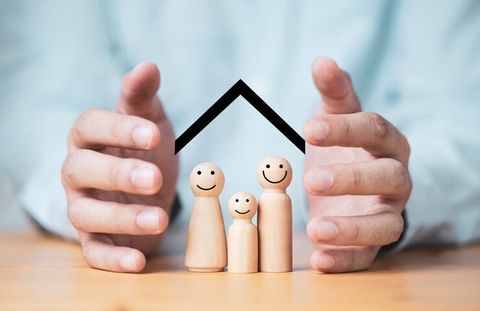
Family protection is not simply about selecting the policy with the longest duration. It involves considering the financial gap that could arise if the insured person dies and how long that gap could remain.
Relevant considerations can include:
Household income provided by the insured person
Number of financially dependent family members
Existing savings and other financial assets
Outstanding debts and long-term obligations
Expected education or caregiving expenses
Planned retirement period
Duration for which income replacement may be needed
Existing life insurance coverage
The National Association of Insurance Commissioners identifies family income, dependent relatives, debts, education expenses, final expenses, and future financial needs among the factors that can be considered when assessing life insurance requirements.
When term life may fit a temporary need
Term life insurance can align with a financial obligation that has an identifiable end point. For example, a household may want income protection while children are dependent or while a substantial debt is expected to remain outstanding.
Its structure can make it easier to match the coverage period with a particular stage of life. However, protection ends when the term ends unless the policy provides a renewal or conversion provision and the applicable conditions are met.
When whole life may fit a lifetime need
Whole life insurance may be relevant when the objective is permanent life insurance protection and the policyholder also wants a cash value component.
The trade-off is greater complexity and generally higher premiums compared with term coverage. Cash value should therefore be examined through the actual policy illustration and contractual provisions rather than through assumptions about future growth.
Recent Updates
From 2024 through 2026, the life insurance sector has continued to experience changes in consumer preferences, financial conditions, investment practices, and regulatory oversight. Industry regulators have also placed attention on insurer financial strength, transparency, capital requirements, and evolving risk-management practices.
Another continuing trend is greater consumer access to digital insurance information. Online questionnaires, electronic applications, digital policy documents, automated underwriting systems, and online policy-management tools have changed how people research and manage life insurance.
These developments do not change the fundamental distinction between term and whole life insurance. Term coverage remains structured around a defined period, while whole life belongs to the permanent or cash-value category.
Greater attention to policy transparency
Recent regulatory discussions have also highlighted the importance of understanding policy values and the assumptions behind products containing cash-value or investment-related features. Regulators have been examining changes in insurer investment practices, reinsurance arrangements, capital requirements, and other factors that can affect the broader life insurance market.
For consumers, this reinforces the importance of distinguishing between contractual values and figures that depend on assumptions, future performance, or non-guaranteed elements.
Digital tools and underwriting
Digital processes have also become more common in life insurance applications. Depending on the insurer and jurisdiction, underwriting may use electronic health information, automated decision systems, data analysis, and remote documentation.
The presence of digital underwriting does not remove the importance of reading policy conditions. Eligibility, premiums, exclusions, coverage limits, renewal provisions, and other terms remain dependent on the individual policy.
Laws or Policies
Life insurance is regulated through national or regional insurance frameworks, so specific legal requirements vary significantly between jurisdictions. Rules can govern licensing, policy wording, disclosures, underwriting practices, financial reserves, claims handling, consumer protections, and insurer solvency.
A major regulatory objective is to help ensure that insurers remain financially capable of meeting their contractual obligations. Regulators may therefore monitor insurer capital, reserves, investments, reporting, and risk management. Recent regulatory work has included attention to changing investment strategies and the increased complexity of certain insurance-market activities.
Policyholders should also understand that a life insurance contract is governed by its written terms. Provisions concerning missed premiums, reinstatement, surrender, loans, cash value, beneficiaries, exclusions, renewal, and conversion can differ between policies.
Policyholder protections
Many jurisdictions have consumer-protection frameworks that provide information and disclosure requirements for life insurance. Some also have insurance guaranty or compensation arrangements intended to provide limited protection under specified circumstances if an insurer becomes financially impaired.
The exact protection, eligibility requirements, and limits depend on the jurisdiction. Therefore, general information about insurance regulation should not be treated as a substitute for the applicable local rules or the actual policy contract.
Tools and Resources
Several tools can help people understand the differences between term life insurance and whole life insurance without relying solely on headline figures.
Life insurance needs calculator
A life insurance needs calculator can help organize potential financial obligations. Common inputs include household income, debts, dependent children, existing assets, education needs, and the period for which financial support may be required.
Calculator results are estimates rather than contractual coverage requirements. They are most useful as a way to structure questions and identify the assumptions behind a coverage amount.
Policy comparison worksheet
A comparison worksheet can place important policy characteristics side by side. Useful fields include:
Coverage amount
Coverage duration
Premium schedule
Renewal provisions
Conversion provisions
Cash value
Surrender provisions
Policy loans
Exclusions
Beneficiary arrangements
Guaranteed and non-guaranteed policy values
Policy illustrations and documents
Whole life policies may include illustrations showing how policy values could develop under particular assumptions. These illustrations should be distinguished from contractual values and should be reviewed alongside the policy's actual terms.
Term policies can also include renewal or conversion information that becomes important near the end of the original coverage period. Understanding these provisions before selecting a policy can provide a clearer picture of how coverage may change over time.
Regulatory resources
National or regional insurance regulators can provide information about licensing, consumer protections, complaint procedures, insurance rules, and insurer oversight. The appropriate regulator depends on where the policyholder resides and where the insurance contract is regulated.
FAQs
Is term life or whole life insurance better for family protection?
Neither type is universally better. Term life insurance may align with a temporary income-replacement need, while whole life insurance is designed for lifetime protection and generally includes cash value. The appropriate structure depends on the household's financial objectives and the duration of its protection needs.
What is the difference between term life and whole life insurance?
Term life insurance provides coverage for a defined period and generally does not accumulate cash value. Whole life insurance is permanent coverage with a cash value component and is generally structured for lifetime protection, subject to its policy conditions.
Does whole life insurance build cash value?
Generally, yes. Whole life policies typically accumulate cash value according to their contractual provisions. The value can be affected by premiums, policy charges, withdrawals, loans, and other provisions, so the actual policy documents are important when assessing the value.
Can term life insurance become whole life insurance?
Some term life policies include a conversion provision that permits conversion to certain permanent coverage. The available conversion period, eligible policies, premium structure, and other conditions depend on the original contract.
Does life insurance protect a family from financial difficulties after death?
Life insurance can provide a death benefit to named beneficiaries when the insured person dies, subject to the policy's terms and applicable conditions. The amount of financial protection depends on the coverage amount and the family's financial needs, so a policy should be considered in the context of the household's overall financial position.
Disclaimer: The information provided in this article is for informational purposes only. We do not make any claims or guarantees regarding the accuracy, reliability, or completeness of the information presented. The content is not intended as professional advice and should not be relied upon as such. Readers are encouraged to conduct their own research and consult with appropriate professionals before making any decisions based on the information provided in this article.